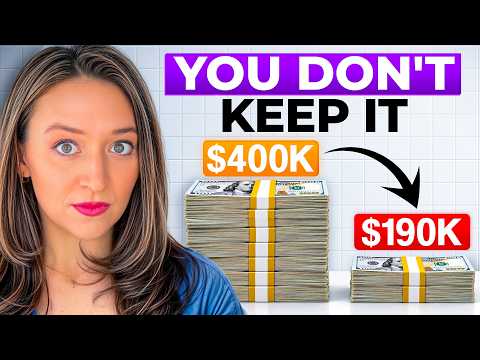
I’m 60 With a $400,000 Windfall—But It’s All I Have
AI Summary
The speaker emphasizes the value of examples in understanding and applying financial concepts to diverse personal circumstances, including income, expenses, assets, and goals. While examples can't perfectly match every situation, they provide a useful framework. The video focuses on a hypothetical case inspired by a clickbait headline: "I'm 60, I just received a $400,000 windfall, and it's the only money I have for retirement. Can I make this work?" The speaker criticizes the original article's analysis for being "lackluster," failing to account for taxes or attorney fees, and simply applying a 4% withdrawal rate. The goal is to provide a more thorough analysis.
To do this, additional details are added to the hypothetical situation. Xavier is 60, single, and received a $400,000 settlement from an age discrimination and wrongful termination claim. Crucial missing information from the original article, such as the settlement allocation, attorney fees, and Xavier's state of residence, are filled in with assumptions. The speaker stresses that employment settlements are complex, and their tax treatment depends on what they are designed to replace.
The hypothetical $400,000 settlement is allocated as follows: $250,000 to back pay and front pay (compensating for lost wages), $100,000 to emotional distress, and $50,000 to punitive damages. This allocation highlights why the details of a settlement are critical. The first "surprise" is that a wrongful termination settlement is generally not tax-free. The $250,000 for lost wages (back pay and front pay) is typically treated as wages and subject to federal income tax, Medicare tax, and Social Security tax, as if Xavier had earned them through traditional employment. The employer would generally report this on a W-2. The $100,000 for emotional distress is usually taxable as ordinary income unless it resulted from a physical injury or sickness. The $50,000 in punitive damages is also generally taxable as ordinary income. The non-wage portions are subject to income tax but typically not Social Security or Medicare tax. The tax treatment mirrors the underlying reason for the settlement, a distinction explained by the IRS.
Next, attorney fees are considered. Employment attorneys often work on a contingency basis, taking a percentage of the recovery. Assuming a 35% fee, Xavier's attorney would receive $140,000, leaving Xavier with $260,000 before taxes. Another tax complication arises: depending on the lawsuit's nature, Xavier could initially be treated as receiving the entire $400,000, including the portion paid to his attorney. However, in certain unlawful discrimination employment claims, attorney fees can qualify as an above-the-line deduction. This assumption is made, preventing Xavier from paying federal income taxes on the attorney's share.
The calculation proceeds:
1. **Gross Settlement:** $400,000
2. **Less Qualifying Attorney Fees:** $140,000
3. **Adjusted Gross Income (AGI):** $260,000
4. **Less Standard Deduction (2026 for single):** $16,100
5. **Taxable Income:** $243,900
Applying 2026 federal income tax brackets, Xavier's estimated federal income tax liability is about $55,000, with his income reaching the 32% marginal bracket. It's clarified that this rate only applies to the highest income portions.
Payroll taxes are then added. The $250,000 allocated to back pay and front pay is subject to Social Security and Medicare taxes. Importantly, the above-the-line attorney fee deduction does not reduce this portion for payroll tax purposes. Using the 2026 Social Security wage base of $184,500, Xavier would owe approximately $11,000 in Social Security tax and $4,000 in regular Medicare tax on the $250,000 wage portion. Additionally, because his Medicare wages exceed $200,000, he would owe about $450 in additional Medicare tax. Total employee payroll taxes are approximately $16,000.
Summarizing the deductions from the $400,000 windfall:
* Attorney fees: $140,000
* Federal income tax: $55,000
* Employee payroll taxes: $16,000
* **Xavier's net after fees and taxes:** Approximately $190,000.
This starkly contrasts the initial $400,000 headline, demonstrating that over half of the settlement was lost to fees and taxes. The speaker emphasizes that this kind of windfall is often a once-in-a-lifetime event, making it crucial to factor in all costs for a realistic understanding of what can be supported financially. State taxes were not included, which could further reduce the net amount. Different attorney fee arrangements or deduction eligibility would also alter the outcome. The core message is that a $400,000 settlement rarely translates to $400,000 of investable assets.
Now, the original question: can Xavier retire at 60 with $190,000?
* With $190,000 invested and no other assets or income, and not yet eligible for Social Security or Medicare:
* 4% withdrawal rate: $7,600 per year
* 5% withdrawal rate: $9,500 per year
* 6% withdrawal rate: $11,400 per year
More aggressive withdrawals increase the risk of depleting the portfolio faster. At 60, Xavier would also need to pay for health insurance until Medicare eligibility at 65. While some might survive on $10,000-$12,000 per year, it's generally not enough for a sustainable retirement for most people.
Therefore, the speaker puts Xavier "back to work."
**Scenario 1: Xavier works until age 65.**
* Assumes Xavier earns $65,000 per year and has employer-sponsored health insurance.
* The $190,000 remains invested and compounds at an assumed 8% annually.
* No additional contributions from salary are made (conservative assumption).
* After 5 years (until age 65), the $190,000 grows to approximately $280,000.
* At 65, Xavier retires and is eligible for Medicare, which makes healthcare more predictable and affordable, though not free.
* Xavier claims Social Security at 65 (early claiming). Assuming average annual earnings of $65,000, his full retirement age (FRA) benefit at 67 would be about $2,500 per month. Claiming at 65 (24 months early) results in a 13% reduction, leading to approximately $2,200 per month or $25,800 per year (in today's dollars).
Combining the portfolio and Social Security at age 65:
* $280,000 invested.
* 4% withdrawal rate: $11,000/year from portfolio + $25,800/year from Social Security = $36,800 gross retirement income.
* 5% withdrawal rate: $14,000/year from portfolio + $25,800/year from Social Security = $39,800 gross retirement income.
* 6% withdrawal rate: $16,800/year from portfolio + $25,800/year from Social Security = $42,600 gross retirement income.
These figures are substantially higher than retiring at 60 with just the settlement.
**Scenario 2: Xavier works until age 67 (full retirement age).**
* Xavier continues earning $65,000 per year for 7 years.
* The $190,000 compounds at 8% for 7 years, growing to approximately $326,000. This is $46,000 more than retiring at 65 and $136,000 more than at 60.
* At 67, Xavier claims Social Security at his full retirement age, avoiding the 13% reduction. His benefit increases to approximately $2,500 per month, an extra $300+ per month or $4,000 per year compared to claiming at 65.
Comparing retirement at 65 vs. 67 (using 5% and 6% withdrawal rates):
* **Retiring at 65:**
* 5% withdrawal: ~$40,000/year
* 6% withdrawal: ~$43,000/year
* **Retiring at 67:**
* 5% withdrawal: ~$46,000/year (from $326k portfolio + $30k SS)
* 6% withdrawal: ~$49,000/year
The additional two years of work significantly boost retirement income. At 67, with a 5% portfolio draw, Xavier's estimated retirement income of $46,000 per year replaces 71% of his gross pre-retirement income of $65,000. This falls within the common guideline of replacing 70-80% of pre-retirement income. While comparing gross employment income to gross retirement income isn't perfect (some expenses decrease in retirement, others like healthcare may increase), $46,000 per year could be workable if Xavier lives in a low-cost area, owns his home outright, and has little debt. However, someone with a large mortgage, high cost of living, or significant debt would need substantially more.
The speaker concludes by reiterating that the initial $400,000 settlement is misleading. After fees and taxes, it's closer to $190,000. Retiring at 60 with only this amount is likely unrealistic. However, by working an additional 5-7 years, securing health coverage, allowing investments to compound, and letting Social Security benefits grow, Xavier can significantly improve his financial security. Key levers for retirement success include a flexible withdrawal rate, time, employment income, healthcare coverage, compounding, additional savings, and the age at which Social Security is claimed. These details are vital for a complete financial picture, unlike simply applying a rule-of-thumb withdrawal rate to a headline number.