Erin Talks Money | Erin Moriarity
AI Audio Summaries
20 videos summarized
1 follower on BriefTube
Last summary: Oct 9, 2026
AI Audio Summaries
20 videos summarized
1 follower on BriefTube
Last summary: Oct 9, 2026
Read AI summary
YouTube
The speaker emphasizes the value of examples in understanding and applying financial concepts to diverse personal circumstances, including income, expenses, assets, and goals. While examples can't perfectly match every situation, they provide a useful framework. The video focuses on a hypothetical case inspired by a clickbait headline: "I'm 60, I just received a $400,000 windfall, and it's the only money I have for retirement. Can I make this work?" The speaker criticizes the original article's analysis for being "lackluster," failing to account for taxes or attorney fees, and simply applying a 4% withdrawal rate. The goal is to provide a more thorough analysis. To do this, additional details are added to the hypothetical situation. Xavier is 60, single, and received a $400,000 settlement from an age discrimination and wrongful termination claim. Crucial missing information from the original article, such as the settlement allocation, attorney fees, and Xavier's state of residence, are filled in with assumptions. The speaker stresses that employment settlements are complex, and their tax treatment depends on what they are designed to replace.
Read AI summary
YouTube
The biggest fear for many people approaching retirement is running out of money. However, data suggests this fear is often more pronounced before retirement than during it. Longitudinal studies tracking individuals over many years reveal that the typical retiree does not deplete their entire portfolio. This contradicts common headlines warning of millions running out of money. The distinction between having very little money at the end of life and spending down a substantial portfolio to zero is crucial. The fear of outliving assets is significant among non-retired investors, with a 2025 survey indicating 53% were concerned. Common anxieties include living too long, market downturns at retirement, persistent inflation, long-term care costs, and making irreversible financial mistakes.
Read AI summary
YouTube
Most Americans will earn millions of dollars throughout their working lives, but whether this translates into wealth depends on how they manage their income. Some income covers living expenses, some pays down a home, some buys company shares through retirement accounts, and some is used to build businesses or acquire rental properties. These decisions determine if one arrives at retirement dependent on a paycheck or supported by assets. This discussion examines assets that build wealth in America, how many families own them, and why wealth varies significantly between households. While a large investment portfolio is often equated with wealth, it's only one aspect. Net worth, defined as assets minus liabilities, includes home equity, investment accounts, retirement accounts, and business interests, less debts like mortgages. However, net worth doesn't reflect how easily assets convert to spendable income, nor does it include reliable income streams like Social Security or pensions. Although these income streams are generally not transferable to heirs, they provide substantial value during one's lifetime. Therefore, both traditional assets and reliable retirement income are crucial for a complete understanding of wealth.
Read AI summary
YouTube
As many as one in ten Medicare Advantage enrollees, totaling approximately 3.5 million Americans, could face plan terminations in 2027. If your plan is among those being discontinued, this situation may present a unique opportunity to acquire a Medigap plan without medical underwriting. However, this opportunity is contingent on the specific reason your plan is ending, your subsequent coverage choice, and, critically, whether you act within the designated timeframe. If you receive a termination notice for your plan, you have important decisions to make. This discussion will outline your available options, pertinent deadlines, and steps to ensure your medical and prescription coverages are secured for January. Even if your plan is not ending, understanding which changes grant special rights and which do not is beneficial. Historically, it was uncommon for Medicare Advantage enrollees to be compelled to seek new plans due to their existing plans exiting the market. Research indicated an average exit rate of approximately 1% annually from 2018 to 2024. This figure increased to 6.9% entering 2025, and for 2026, about 2.9 million individuals, roughly one in ten enrollees studied, were impacted by plan exits. For 2027, insurers are announcing further changes. Humana, for instance, anticipates its plan exits alone will affect around 600,000 members. Current industry estimates suggest that up to 10% of Medicare Advantage enrollees could be impacted by terminations in 2027. While the 2026 figures are based on confirmed data, the 2027 estimate, representing roughly 3.5 million people, is substantial and will be finalized with the release of 2027 plans. The immediate goal is to ensure that anyone receiving a termination notice understands their subsequent options.
Read AI summary
YouTube
Owen Zidar, a professor of economics at Princeton University and co-author of "The Everywhere Millionaire," discusses the true nature of America's wealthy. Contrary to popular belief that millionaires are often young, extravagant celebrities or executives, Zidar explains that the typical millionaire is usually someone who owns an unglamorous, often tactile, private business. These include auto dealers, beverage distribution companies, or owners of multiple franchises. Zidar's work builds upon and updates the findings of "The Millionaire Next Door," but with a crucial difference: his research utilizes the full population data of wealthy Americans, rather than relying on surveys which often miss responses from the rich. This allows for a more representative picture of wealth. He defines "everywhere millionaires" as individuals with $5 million or more in net worth, placing them in the top 4% of the national wealth distribution, and including all assets less liabilities, such as houses, private businesses, and stocks. He notes that the $5 million threshold is used to avoid the common pushback that $1 million today doesn't feel as significant due to inflation and rising housing costs.
Read AI summary
YouTube
The 457 retirement account, while appearing similar to a 401k, possesses a unique feature that sets it apart: the ability to withdraw funds immediately upon separating from employment, at any age, without incurring the typical 10% early withdrawal penalty. This makes it an incredibly powerful tool for those considering early retirement. However, it's not universally available, primarily offered to state and local government employees, certain tax-exempt nonprofits, and their employees, such as teachers, police officers, firefighters, EMTs, public librarians, transit workers, judges, public defenders, and employees of public universities and school districts. It's crucial to understand that there are two distinct types of 457 plans: governmental 457 plans and non-governmental (or "top hat") 457 plans, despite sharing the same name. Governmental 457 plans are offered by states, counties, cities, police and fire departments, public universities, and public school districts. The assets in these plans are held in a trust for the employees, offering the same protections as other standard retirement accounts. In contrast, non-governmental 457 plans, typically offered by certain nonprofits, hospitals, universities, and to executives at nonprofit organizations, mean that your money remains the property of your employer until distributed. This distinction is critical because if the employer becomes insolvent, the retirement savings in a non-governmental 457 could potentially be subject to their creditors. Therefore, the first step for anyone with a 457 plan is to identify which type they have, as it impacts the safety of their money and the applicability of certain rules.
Read AI summary
YouTube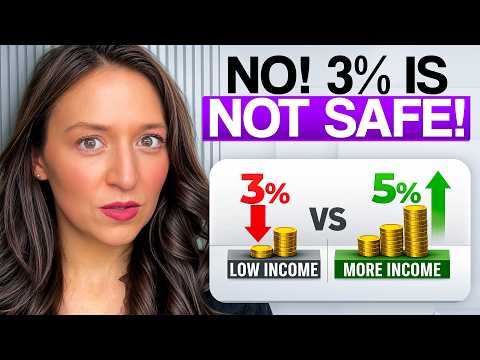
The discussion revolves around safe withdrawal rates in retirement, particularly challenging the common belief that a 3% withdrawal rate is universally appropriate. For the majority of retirees, a 3% rate is considered overly conservative, leading to over-restriction in retirement and under-living. Current forward-looking research, notably from Morningstar, estimates a safe withdrawal rate of approximately 3.9% for a 30-year retirement in 2026. This number was 3.7% in 2025 and briefly over 4% in 2023 when yields were higher. This suggests a current range of 3.7% to 3.9% as a center of gravity for planners. It's important to note that these figures are derived from Monte Carlo simulations, which are forward-looking, intentionally conservative, assume lower future returns, stress test against a wide range of outcomes, and build in a margin of safety. Therefore, even these rates are based on a very conservative framework.
Read AI summary
YouTube
The definition of a "millionaire" can be quite nuanced, leading to discrepancies in reported figures. For instance, the US has approximately 23.6 million adult millionaires, representing about 9% of the population. However, only 8.7 million Americans are considered "high net worth individuals." This difference arises from what assets are included in the calculation. Traditional net worth encompasses everything you own minus everything you owe, including your primary residence, investment properties, retirement accounts, brokerage accounts, cash, business interests, vehicles, and other valuable property, minus mortgages, student loans, auto loans, credit card balances, and other debts. Someone with a million-dollar home and $200,000 in mortgage debt, along with $300,000 in a 401k, would have a net worth of $1.1 million, making them a millionaire. In contrast, the financial services industry typically uses a more stringent definition for high net worth individuals, focusing on $1 million in investable assets. This generally includes cash, publicly traded stocks, bonds, mutual funds, private equity holdings, offshore investments, and investment real estate. It explicitly excludes a primary residence, collectibles, consumer durables, and personal possessions. Therefore, owning a million-dollar home contributes to traditional millionaire status but not to the high net worth classification.
Read AI summary
YouTube
The speaker expresses admiration for George Kamel and the entire Ramsey team, acknowledging a prior collaboration and recent video by George titled "The Biggest Ponzi Scheme Ever" about Social Security. While respecting George and appreciating the attention he brings to the topic, the speaker disagrees with parts of his argument, particularly the assertion that Social Security is a Ponzi scheme and that workers lose millions in potential investment growth. Both agree that individuals are their best shot at a great retirement and should save, invest, and build wealth outside of Social Security. The core disagreement lies in George's calculation that workers could create millions by investing what they pay in Social Security taxes. The speaker argues this idea mixes dollars from different decades and overlooks crucial aspects of what Social Security provides.
Read AI summary
YouTube
Jason Fickner, former deputy commissioner of the Social Security Administration and current executive director of the Limra Retirement Income Institute, discusses the state of Social Security, offering insights for different age groups and addressing common misconceptions. For individuals in their 50s and 60s, Fickner advises cautious optimism rather than excessive worry about Social Security. He clarifies that the projected depletion of the primary trust fund for retirement in 2032 does not mean bankruptcy. Instead, it implies that Social Security would only be able to pay out approximately 78% of benefits based on current revenues, primarily payroll taxes. He emphasizes that even in a worst-case scenario where Congress takes no action, benefits would still be around 80%. Most reform plans circulated tend to protect current retirees or those 50-55 and older from benefit cuts, possibly only slowing the growth of cost-of-living allowances. Fickner encourages this demographic to urge Congress to act now for better planning.
Read AI summary
YouTube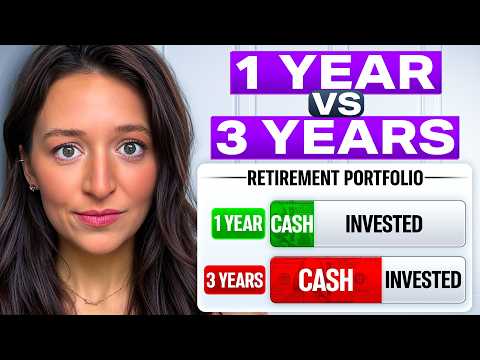
Retirees are often advised to keep a significant amount of cash on hand, typically one to five years of living expenses, to avoid selling investments during market downturns. However, new research from Vanguard suggests that holding too much cash can actually be detrimental to a retirement plan, potentially costing hundreds of thousands of dollars over time. Vanguard modeled a 60-year-old individual with a $250,000 portfolio, withdrawing $20,000 annually. In one scenario, the retiree kept one year's worth of withdrawals in cash, approximately $20,000. In another, they held three years' worth, around $60,000. All other factors, including portfolio and withdrawal amounts, remained the same. By age 75, the retiree with one year of cash had about $106,000 remaining, while the one with three years had only $68,000. By age 80, this gap widened dramatically, with the one-year cash holder having $58,000 left, compared to just $9,000 for the three-year cash holder. This striking difference, despite identical starting portfolios and withdrawal rates, highlights the significant impact of cash reserves.
Read AI summary
YouTube
The Congressional Budget Office (CBO) has presented a counterintuitive scenario regarding Social Security: if Congress takes no action and benefits are automatically cut in 2032, the economy could end up larger in a few years than if benefits had remained unchanged. It's crucial to understand that this is a modeled scenario and not a prediction or an endorsement of benefit cuts. The context for this discussion is that Social Security's Old Age and Survivors Insurance Trust Fund is projected to run out of money in 2032. This does not mean the Social Security program itself ends, but rather that by law, it can only pay out what it collects in payroll taxes. Historically, payroll tax revenue has been stable at 4-4.5% of GDP, while payouts have risen due to more retirees living longer. If the trust fund hits zero without reforms, current benefits would be cut. The Social Security Trustees project a 22% cut, meaning a $2,000 monthly benefit would become $1,560. The CBO's modeling, which this discussion is based on, projects a shortfall starting smaller in 2032 and climbing to an average of 28% by 2036.
Read AI summary
YouTube
The video explores the concept of emotional intelligence (EQ) and its significant impact on career success and financial well-being, arguing that it's a crucial skill often overlooked. It contrasts two individuals with similar starting points: one earns $120,000 annually after 20 years, while the other leads a company, manages 30 people, and earns $300,000, possessing a vast professional network. The difference, the video posits, isn't necessarily higher IQ or more work, but a superior skill in emotional intelligence. Traditionally, success was believed to hinge on cognitive abilities: intelligence, good grades, degrees, and credentials. These are indeed vital for entering professions like medicine or law, where they act as a filter. However, once individuals reach a certain level, they find themselves surrounded by equally intelligent and competent peers. At this stage, cognitive ability alone is no longer the primary differentiator for advancement.
Read AI summary
YouTube
Retirement is often portrayed as a predictable finish line, a stable period with a consistent budget and predictable expenses. However, data from JP Morgan's Guide to Retirement reveals a starkly different reality for many retirees. Life, with its unexpected events, continues to unfold, and retirement is no exception. This presentation aims to shed light on the true nature of retirement spending, focusing on "spending shocks" – unpredictable and significant increases in expenses – and how to build a resilient retirement plan that can withstand them. The conventional approach to retirement planning often relies on a simplified model: an initial spending amount adjusted annually for inflation. This "flat line" or "gentle slope" model, while mathematically clean, is largely fictional. Real retirees experience life's unpredictability, including events like car accidents, medical emergencies, home repairs, and family needs. These real-world occurrences create significant spending volatility that traditional calculators fail to account for. JP Morgan's analysis of millions of actual retiree transactions shows that retirement spending is more akin to a wave, often with unexpected large spikes.
Read AI summary
YouTube
Senator Dr. Bill Cassidy highlights the urgency of addressing Social Security's financial situation, describing it as "mostly dead" but not yet a full crisis. He explains that the Social Security trust fund is currently being drained to cover the gap between benefits paid out and contributions received. In six years, around 2032 or 2033, the trust fund is projected to be empty. By law, this would necessitate an immediate cut of up to 28.5% in benefits for all current and future recipients. Alternatively, if Congress funds the shortfall from the general fund without fixing the underlying problem, it would lead to a massive increase in national debt, higher inflation, and a collapse in the bond market, making essential purchases like homes unaffordable. Both scenarios are "awful," and the problem must be fixed. Cassidy notes that Congress is unlikely to act unless forced, as they tend to avoid tough political decisions. He and Senator Dick Durbin are attempting to compel action now, rather than waiting until the crisis point, which would require even more drastic cuts or tax increases. He criticizes the current political climate where fear of criticism on social media prevents meaningful action.
Read AI summary
YouTube
Traditional financial advice often suggests saving a fixed percentage, such as 15% or 20%, of every paycheck from one's 20s until retirement. This approach is simple and memorable, but an entire branch of economics, known as life cycle saving or the life cycle hypothesis, posits that this might not be the optimal strategy for real life. Instead, the goal should be to maintain a reasonable, stable lifestyle throughout one's life, rather than saving the same percentage every year. The life cycle model of consumption, a core principle in economics, distinguishes itself from conventional advice by advocating for saving an amount that best balances current needs with future needs. It suggests people move through three financial phases: early adulthood (low income, high expenses), peak earning years (increased income, declining early expenses), and retirement (no employment income, living off accumulated assets). The theory proposes using saving and sometimes borrowing to smooth out consumption, meaning maintaining a consistent standard of living, across a lifetime. This doesn't imply frivolous spending but rather covering essential goods and services like housing, food, healthcare, and vacations.
Read AI summary
YouTube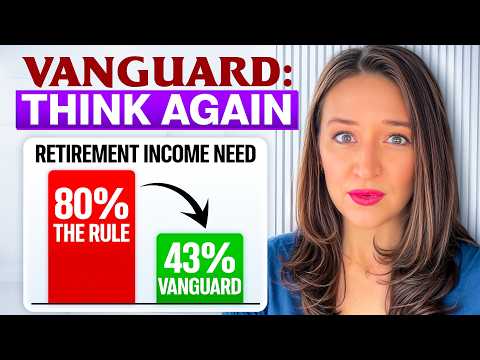
The common retirement planning guideline suggests needing 70% to 80% of your pre-retirement income. However, Vanguard's research indicates this rule is misleading, especially for higher earners. For instance, someone earning $22,000 annually might need closer to 96% of that income in retirement, while a middle-income earner needs about 83%. In stark contrast, someone earning $173,000 annually might only need around 43% of their pre-retirement income, which translates to roughly $74,000, not the $138,000 that an 80% rule would suggest. This significant $64,000 annual gap, if based on an inflated retirement target, could lead to an overestimation of the required retirement portfolio by approximately $1.6 million, calculated using a simplified 4% withdrawal rate. The rationale behind the 70-80% rule is that certain expenses diminish or disappear upon retirement. These include retirement contributions, payroll taxes on wages, commuting and work-related costs, potentially a paid-off mortgage, financially independent children, lower income taxes, and already funded savings goals. The logic is that you don't need 100% of your pre-retirement income to maintain the same lifestyle. The 80% figure became a popular rule of thumb because it's simple and provides a target for those unsure about their specific retirement spending needs, potential expense reductions, Social Security benefits, or future tax situations.
Read AI summary
YouTube
Social Security benefits are projected to increase by 3.5% to 3.6% in 2027, potentially adding an extra $73 to $75 per month for an average worker. However, the actual amount beneficiaries get to keep will be affected by rising Medicare Part B premiums, shifting prescription drug costs, and potential Income Related Monthly Adjustment Amounts (IRMAA) for high-income retirees. The 2027 numbers are still projections and not yet finalized. The Social Security cost of living adjustment (COLA) is expected to be between 3.5% and 3.6%, with the final figure announced on October 14th. The standard Medicare Part B premium is projected to be around $29.50, and the official announcement will come later this fall. IRMAA income thresholds are projected at $112,000 for single filers and $224,000 for joint filers, with official announcements alongside Part B premiums.
Read AI summary
YouTube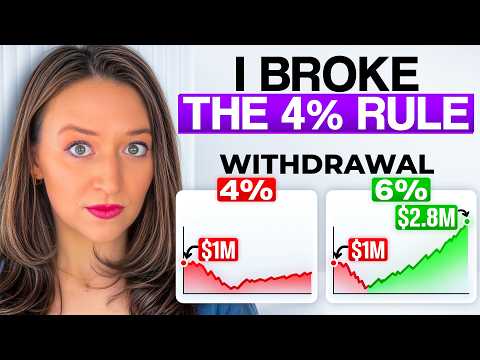
The 4% rule is a widely discussed guideline for retirement withdrawals. It suggests taking 4% of your portfolio in the first year of retirement, and then adjusting that dollar amount for inflation in subsequent years. This means that only in the first year are you actually withdrawing 4% of your portfolio; in all following years, you are simply maintaining purchasing power against rising prices. This rule is based on historical data and rolling 30-year periods, aiming to minimize the risk of running out of money in retirement. The financial industry and investors often adhere strictly to this rule due to the significant fear of depleting retirement funds. Any suggestion of withdrawing more than 4% often meets resistance, despite examples demonstrating that higher withdrawal rates can be sustainable under certain conditions. One key issue with the rigid 4% rule is that life and spending are not static. Research on large populations of retirees indicates that spending patterns tend to change over time. Typically, there's a greater desire to spend more in the early years of retirement. As individuals enter their 70s, spending often tapers, and it may decline further in their 80s and 90s. This general decline is estimated to be about 1% to 2% per year. For instance, RAND research, using health and retirement study data, found that single retirees experienced an annual real spending decline of about 1.7% after age 65, while couples saw a decline of approximately 2.4% annually. This trend was observed across all wealth levels, with the wealthiest households showing the steepest decline. David Blanchett's research also supports this, finding that inflation-adjusted spending fell roughly 26% between ages 65 and 84, which averages out to about 1.6% per year compounded. His newer research suggests that retiree spending generally continues to decline throughout retirement, rather than experiencing an uptick later in life.
Read AI summary
YouTubeBriefTube monitors your YouTube channels, generates AI-powered audio summaries, and delivers them wherever you listen. Telegram, Discord, Slack, or your podcast app. Fully automated.
Start free trial