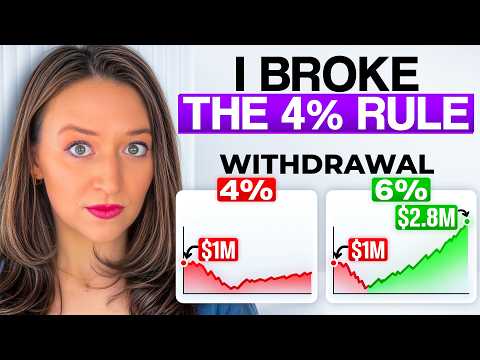
I Broke the 4% Rule—and the Portfolio Ended With $2.8 Million
AI Summary
The 4% rule is a widely discussed guideline for retirement withdrawals. It suggests taking 4% of your portfolio in the first year of retirement, and then adjusting that dollar amount for inflation in subsequent years. This means that only in the first year are you actually withdrawing 4% of your portfolio; in all following years, you are simply maintaining purchasing power against rising prices. This rule is based on historical data and rolling 30-year periods, aiming to minimize the risk of running out of money in retirement. The financial industry and investors often adhere strictly to this rule due to the significant fear of depleting retirement funds. Any suggestion of withdrawing more than 4% often meets resistance, despite examples demonstrating that higher withdrawal rates can be sustainable under certain conditions.
One key issue with the rigid 4% rule is that life and spending are not static. Research on large populations of retirees indicates that spending patterns tend to change over time. Typically, there's a greater desire to spend more in the early years of retirement. As individuals enter their 70s, spending often tapers, and it may decline further in their 80s and 90s. This general decline is estimated to be about 1% to 2% per year. For instance, RAND research, using health and retirement study data, found that single retirees experienced an annual real spending decline of about 1.7% after age 65, while couples saw a decline of approximately 2.4% annually. This trend was observed across all wealth levels, with the wealthiest households showing the steepest decline. David Blanchett's research also supports this, finding that inflation-adjusted spending fell roughly 26% between ages 65 and 84, which averages out to about 1.6% per year compounded. His newer research suggests that retiree spending generally continues to decline throughout retirement, rather than experiencing an uptick later in life.
To illustrate this, consider someone spending $80,000 annually at age 65 (in today's purchasing power). With a 1% annual decline, their spending would be $76,100 by age 70, $72,400 by 75, $68,800 by 80, and $65,000 by 85. If a more aggressive 2% annual decline is used, starting at $80,000 at 65, spending would be $72,000 by 70, $65,000 by 75, $59,000 by 80, and $53,000 by 85. This significant reduction in household spending over a 30-year period, potentially by half, should influence retirement planning and sustainable withdrawal patterns. These figures are inflation-adjusted, highlighting a real decrease in spending.
The 4% rule was established based on historical data, specifically representing the highest sustainable withdrawal rate that could withstand the most challenging economic periods, such as a retiree starting in October 1968 and experiencing market declines, weak returns, and the high inflation of the 1970s. Even under these conditions, using what Bill Bengen termed the "SafeMax" rate, the retiree would not have run out of money. Bengen later updated his research, adjusting the SafeMax rate to about 4.7% by incorporating a broader range of asset classes, but the core principle of a fixed withdrawal adjusted for inflation remained.
Given that many retirees desire to spend more in their early retirement years and then naturally see spending taper, an alternative approach can be explored. Let's revisit the 1968 scenario, but instead of a fixed 4% withdrawal, consider a higher initial withdrawal rate with planned spending reductions over time.
For this example, assume a retiree has a $1 million portfolio. While this exact amount isn't tied to 1968, the inflation and market returns from that period are used for the simulation. The assumptions are: a 6% initial withdrawal rate, inflation adjustments applied in years two through four alongside a 2% real reduction in withdrawals each year, and then the withdrawal amount is permanently frozen starting in year five.
Here's how this plays out:
- Year 1: Initial 6% withdrawal of $60,000.
- Year 2: With inflation adjustment and 2% real reduction, withdrawal is $62,000.
- Year 3: Similar adjustments, withdrawal is about $65,000.
- Year 4: Similar adjustments, still around $65,000.
- Years 5-30: The withdrawal is frozen at $65,380 annually, with no further inflation adjustments.
Analyzing the portfolio's performance from October 1968:
- Year 1: Portfolio declines to about $879,000.
- Year 2: Fairly flat.
- Years 3-4: Portfolio rebounds slightly.
- Years 5-6: Steep decline.
- Year 7: Slight rebound.
- Years 10-15: Hit hard again.
- Year 20: Portfolio exceeds $1 million.
- Year 25: Nears $1.5 million.
- Year 30: Reaches almost $3 million.
This might appear as a significant success, with the portfolio not only surviving a 6% initial withdrawal but also growing to nearly 2.8 times its starting balance. However, there's a crucial caveat: the withdrawals were frozen from year five onwards, while inflation continued. This means the purchasing power of the $65,000 withdrawal steadily eroded.
In terms of year one purchasing power:
- Year 4: About $56,000.
- Year 6: About $50,000.
- Year 10: $37,000.
- Year 20: About $20,000.
- Year 30: About $14,000.
By year 30, the retiree receives $65,000 nominally, but its real purchasing power is equivalent to only $14,000 from year one, representing a 76% reduction in real spending power. While the portfolio looks strong on paper, the retiree would experience a severe squeeze on their actual living expenses.
This analysis is incomplete without factoring in Social Security. Social Security benefits are inflation-adjusted annually, irrespective of market performance, which helps maintain purchasing power even if portfolio withdrawals are frozen.
Let's incorporate a Social Security benefit of $2,300 per month, or $27,600 per year, starting in year one. The initial 6% portfolio withdrawal ($60,000) combined with Social Security means the retiree lives on just under $90,000 in year one. The Social Security benefit maintains its $27,600 purchasing power due to annual inflation adjustments.
With Social Security:
- Year 1 total income: $87,600.
- Year 2 total income: $86,400 (98.6% of year one purchasing power).
- Year 4 total income: About $84,000 (96% of original purchasing power).
- Year 6 total income: About $78,000 (89% of original purchasing power).
- Year 10 total income: Just under $65,000 (74% of year one purchasing power).
- Year 20 total income: About $48,000 (55% of original purchasing power).
- Year 30 total income: About $42,000 (48% of original purchasing power).
By year 30, the nominal income is about $191,000, but its purchasing power is $42,000 in year one dollars, roughly 48% of the initial amount. For a single filer, total nominal portfolio withdrawals are about $2 million, total nominal Social Security is about $2.2 million, making total nominal income around $4.2 million. Social Security is a crucial component of retirement income.
Medicare is another significant factor. Choosing the right Medicare plan can impact disposable income.
Now, consider a household with two Social Security checks, each $2,300 a month, totaling $4,600 a month or $55,000 a year, in addition to the $60,000 year one portfolio draw. Both Social Security checks receive annual inflation adjustments, maintaining their combined $55,000 purchasing power.
With dual Social Security benefits:
- Year 1 total income: About $115,000.
- Year 2 purchasing power: About $114,000 (99% of year one).
- Year 4 purchasing power: About $112,000 (97% of year one).
- Year 6 purchasing power: About $105,000 (92% of year one).
- Year 10 purchasing power: About $93,000 (80% of year one).
- Year 20 purchasing power: Equivalent to $75,000 (65% of year one).
- Year 30 purchasing power: Equivalent to $70,000 (60% of year one).
By year 30, the nominal income is about $316,000, translating to roughly $70,000 in year one purchasing power, or 60% of the original. For dual filers, total nominal portfolio withdrawals are $2 million, total nominal Social Security is $4.5 million, and total nominal income is about $6.4 million. Total income in year one dollars is about $2.6 million.
Comparing these results to the RAND research on declining spending:
- A single household with spending declining at 1.7% annually for 30 years would end up spending 60% of their year one amount. Our single filer model, with frozen withdrawals and Social Security, resulted in 48% of year one purchasing power.
- A two-person household with spending declining at 2.4% annually would end up spending 48% of their year one amount. Our dual filer model resulted in 60% of year one purchasing power.
- Using a 2% midpoint decline, spending lands around 55%.
Our modeled households fall within the broad range of the RAND data, supporting the idea that spending naturally declines over time, and with inflation-adjusted Social Security, retirees often rely less heavily on their portfolio as retirement progresses.
Important caveats exist. In a dual-income household, it's unlikely both partners will survive 30 years, altering spending and income needs. Additionally, freezing inflation adjustments indefinitely is improbable in a real-world scenario. A more realistic approach would involve pausing inflation adjustments during challenging market periods, allowing the portfolio to recover, and then resuming adjustments to