Vanguard Says You May Need Just 40% of Your Income to Retire
AI Summary
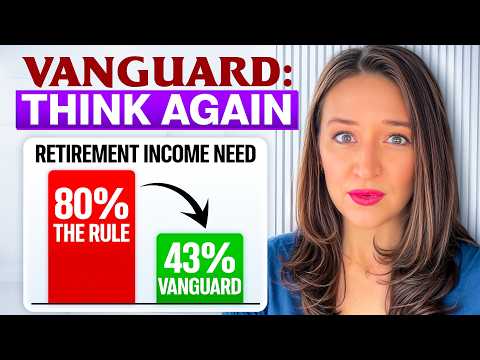
The common retirement planning guideline suggests needing 70% to 80% of your pre-retirement income. However, Vanguard's research indicates this rule is misleading, especially for higher earners. For instance, someone earning $22,000 annually might need closer to 96% of that income in retirement, while a middle-income earner needs about 83%. In stark contrast, someone earning $173,000 annually might only need around 43% of their pre-retirement income, which translates to roughly $74,000, not the $138,000 that an 80% rule would suggest. This significant $64,000 annual gap, if based on an inflated retirement target, could lead to an overestimation of the required retirement portfolio by approximately $1.6 million, calculated using a simplified 4% withdrawal rate.
The rationale behind the 70-80% rule is that certain expenses diminish or disappear upon retirement. These include retirement contributions, payroll taxes on wages, commuting and work-related costs, potentially a paid-off mortgage, financially independent children, lower income taxes, and already funded savings goals. The logic is that you don't need 100% of your pre-retirement income to maintain the same lifestyle. The 80% figure became a popular rule of thumb because it's simple and provides a target for those unsure about their specific retirement spending needs, potential expense reductions, Social Security benefits, or future tax situations.
However, the core issue with a simplified rule like the 80% guideline is its one-size-fits-all approach. It treats a $22,000 earner and a $173,000 earner identically, assuming similar spending patterns, which is fundamentally inaccurate. It's crucial to remember that a replacement rate compares retirement income or spending to pre-retirement *gross* earnings. Furthermore, retirement income isn't solely from a portfolio; it's a combination of sources like Social Security, pensions, annuities, part-time work, and portfolio withdrawals.
Vanguard's 2026 report findings, when rounded, suggest replacement rates of 96% for low earners, around 80% for middle-income earners, and as low as 40% for high earners. The underlying study provides more precise figures: 96%, 83%, 68%, and 43% across different income percentiles.
Let's examine these income levels more closely:
* **The $22,000/year Earner (25th percentile):** Vanguard estimates their spending need at about 96% of pre-retirement income, or roughly $21,120. At this income level, most earnings are likely allocated to essential living expenses, leaving little room for income reduction after work stops. The 80% rule would suggest $17,600, creating an annual shortfall of about $3,500, or a 17% underestimate. While every dollar is critical here, Social Security's progressive nature can significantly offset this need. For this individual, Social Security might replace about $16,000, leaving a gap of roughly $5,100. With consistent savings from their 20s and a 6% real rate of return, this could require a lifetime savings rate of just 2.7%, or about $50 per month. This highlights how Social Security carries a substantial portion of the burden for lower earners, reducing their reliance on personal portfolios.
* **The $42,000/year Earner (50th percentile - median):** Vanguard estimates an income replacement need of about 83%, equating to approximately $34,800. The 80% rule suggests $33,600. The gap here is only about $1,300, making the 80% rule reasonably accurate for this group, which might explain its industry popularity due to the focus on the median.
* **The $61,000/year Earner (70th percentile):** The spending rate here is about 68%, or roughly $41,000. The 80% rule would target $49,000, overstating the need by over $7,000 annually. This difference begins to accumulate.
* **The $173,000/year Earner (95th percentile):** The income replacement rate is about 43%, or approximately $74,000. The 80% rule suggests $138,000, an overstatement of $64,000 annually. While this high earner spends more in absolute dollars, their spending doesn't scale proportionally with their income. Their income is about eight times higher, but their retirement spending need might only be about three and a half times higher.
The pattern is clear: the 80% rule tends to *understate* needs for lower earners and *overstate* them for higher earners, with the overstatement becoming more dramatic at higher income levels.
Several primary reasons explain why the replacement *percentage* decreases as income increases:
1. **Essential Expenses Don't Scale with Income:** Basic living costs like food, utilities, and healthcare don't increase at the same rate as income. An individual earning eight times more doesn't consume eight times more food or energy. While higher earners spend more overall, the fundamental costs of living are not proportionately higher.
2. **Higher Earners Typically Save More Dollars:** High earners often direct significant portions of their income to savings vehicles like 401(k)s, IRAs, brokerage accounts, deferred compensation, and 529 plans. While these are wise uses of income, they are not necessarily expenses that will continue into retirement. Vanguard's study doesn't quantify savings rates for these groups, so this is a contributing factor, not the sole explanation.
3. **Taxes Diminish Top-Line Income:** The replacement rate is calculated against gross income. Federal, state, and payroll taxes, along with potential additional Medicare taxes for higher earners, reduce the amount of spendable income. When employment stops, payroll taxes cease. The tax liability in retirement depends on the source of withdrawals, with some accounts being taxable and others not.
4. **Work-Related Expenses:** The act of working itself incurs costs such as commuting, parking, professional attire, convenience meals, licensing fees, and unreimbursed travel. These expenses may decrease or disappear in retirement, depending on individual circumstances.
5. **The "Expensive Middle Years" May Be Ending:** High earners in their final working years often face significant expenses related to children's education, mortgage payments, home renovations, multiple vehicles, and aggressive catch-up retirement contributions. Many of these costs naturally decline or conclude as retirement approaches.
A case study from Vanguard illustrates this with a couple aged 58, with a combined income of $185,000 and $464,000 in savings. They plan to retire at 67 with projected savings of $1.2 million and combined Social Security of $63,000 annually. Their income target is $85,000, requiring only about $22,000 from their portfolio, resulting in an initial withdrawal rate of a mere 1.8%. Their personal replacement rate is approximately 45.9%, remarkably close to the 43% for the 95th percentile. The 80% rule would have suggested $148,000, overstating their needs by $63,000 annually. This is achievable because Social Security covers about 74% of their needs, and they are not withdrawing heavily from their portfolio. They were also not living on their full income during their working years, and many expenses have fallen away. Vanguard suggests strategies like Roth conversions to optimize their situation, potentially increasing legacy amounts and reducing lifetime taxes.
It's important to note that a lower replacement *percentage* for higher earners does not mean a lower *dollar amount*. The $173,000 earner's need of $74,000 is still significantly higher than the $22,000 earner's $21,000 need. While higher earners need a smaller portion of their income, they likely require a substantially higher absolute dollar amount. Social Security also replaces a smaller percentage for higher earners due to its progressive nature, meaning they may need to save more to fund their retirement.
The discrepancy highlighted by the 80% rule can have significant consequences. Higher earners might unnecessarily tighten their belts, make excessive sacrifices, delay travel or family gifts, or work longer than desired to inflate their savings. While having excess funds in retirement is preferable to having too little, trading years of one's life to overfund a portfolio is a trade-off some may not want to make.
Vanguard also tracks actual spending among retired households aged 65-69. For a single retiree, total annual spending averages around $48,000, with essentials comprising about $40,000 and discretionary spending around $7,400. For a married couple, total annual spending is approximately $72,500, with essentials at $62,000 and discretionary at $11,000. These figures align closely with the percentile data, reinforcing their plausibility.
Instead of replacing one arbitrary number with another, the recommendation is to determine your personal retirement number by following these steps:
1. **Identify Current Spending:** Track all your expenses, including those in checking and credit card accounts, taxes, and insurance.
2. **Remove Disappearing Expenses:** Subtract costs that will cease in retirement, such as retirement contributions, payroll taxes, commuting, child-related expenses (if applicable), and a paid-off mortgage.
3. **Add New or Increased Expenses:** Account for costs that may arise or increase in retirement, such as Medicare premiums, supplemental health insurance, out-of-pocket healthcare, travel, hobbies, home maintenance, long-term care planning, gifts, and taxes on retirement withdrawals.
4. **Categorize Spending:** Separate expenses into categories like discretionary, essential, contingencies, and legacy planning. This provides a clearer understanding of where money is going.
5. **Subtract Reliable Income:** Deduct predictable income streams like Social Security, pensions, or annuities from your total retirement income need. The remainder is the "gap" your portfolio must cover.
6. **Calculate Your Personal Replacement Rate:** Divide your planned retirement spending by your pre-retirement gross income. This number is unique to your lifestyle.
It's crucial to understand that the replacement rate doesn't dictate savings rates or retirement age. These factors must be modeled separately. An early retiree may need a more conservative withdrawal rate than someone retiring later.
In conclusion, simplified retirement rules like the 80% guideline can be a starting point but fail to accurately capture individual circumstances. While it may be close for median earners, it can significantly underestimate needs for lower earners and dramatically overstate them for higher earners. Building your retirement plan